Use this free car insurance calculator to see what you will likely pay each month, with no name, email, phone number or ZIP code needed. Your estimate shows up right away.
Car insurance cost calculator
No name, email, phone or ZIP code. Pick your options and get an estimate in one click.
Written by: VehiclesInformation Editorial Team · Fact-checked against: state insurance department rules and 2026 rate data (our methodology) · Last reviewed: October 2026
How to use the car insurance calculator
- Pick your state. State is the single biggest factor in price. Full coverage costs about $85 a month in New Hampshire and over $300 in Maryland.
- Choose your vehicle type and model year. Newer, faster and more expensive cars cost more to repair, so they cost more to insure.
- Add the driver’s age range, driving record and yearly miles. These are not personal details. They are the same groups insurers use to set prices.
- Set your deductible and credit tier. Both are optional. Leave credit on “Not sure” if you do not know it.
- Pick a coverage level and press Calculate. You get a monthly, six-month and yearly estimate, a price range, and a side-by-side look at all three coverage levels.
How we work out your estimate
Every estimate starts with the average monthly price in your state for full coverage and for liability-only cover, based on 2026 market rates for drivers aged 20 to 70 with a clean record. We then adjust that number for each answer you give.
- Driver age: teen drivers pay about 2.6 times more than a driver aged 35 to 54. Prices fall fast after 25 and rise a little after 65.
- Driving record: one ticket adds about 22%, one at-fault accident about 45%, and a DUI about 85%.
- Vehicle type: minivans and pickups are the cheapest to cover. Sports, luxury and electric cars cost the most because repairs and parts cost more.
- Car age: collision and comprehensive cost less as a car loses value. Liability cover does not change much.
- Deductible: moving from $500 to $1,000 cuts the collision and comprehensive part of your bill by about 12%.
- Miles per year: under 7,500 miles saves about 8%. Over 15,000 miles adds about 8%.
- Credit: poor credit can raise prices by 60% or more. California, Hawaii, Massachusetts and Michigan limit or ban this, so the calculator skips credit in those states.
The result is shown as a range of 15% above and below your number. Two people with the same answers can still get different prices, because each insurer weighs these factors in its own way.
Average car insurance cost by state (2026)
Across all 50 states and Washington, D.C., full coverage averages about $175 a month ($2,100 a year) and liability-only cover averages about $98 a month. New Hampshire, Wyoming and Idaho are the cheapest. Maryland, Rhode Island and Delaware are the most expensive.
| State | Full coverage (monthly) | Liability only (monthly) | Full coverage (yearly) |
|---|---|---|---|
| Alabama | $142 | $66 | $1,704 |
| Alaska | $150 | $70 | $1,800 |
| Arizona | $162 | $91 | $1,944 |
| Arkansas | $150 | $73 | $1,800 |
| California | $203 | $98 | $2,436 |
| Colorado | $217 | $97 | $2,604 |
| Connecticut | $225 | $162 | $2,700 |
| Delaware | $262 | $166 | $3,144 |
| District of Columbia | $237 | $136 | $2,844 |
| Florida | $236 | $142 | $2,832 |
| Georgia | $259 | $157 | $3,108 |
| Hawaii | $126 | $62 | $1,512 |
| Idaho | $107 | $64 | $1,284 |
| Illinois | $162 | $84 | $1,944 |
| Indiana | $128 | $64 | $1,536 |
| Iowa | $111 | $56 | $1,332 |
| Kansas | $157 | $79 | $1,884 |
| Kentucky | $194 | $121 | $2,328 |
| Louisiana | $209 | $106 | $2,508 |
| Maine | $139 | $74 | $1,668 |
| Maryland | $302 | $191 | $3,624 |
| Massachusetts | $137 | $103 | $1,644 |
| Michigan | $229 | $130 | $2,748 |
| Minnesota | $182 | $93 | $2,184 |
| Mississippi | $186 | $89 | $2,232 |
| Missouri | $180 | $92 | $2,160 |
| Montana | $139 | $62 | $1,668 |
| Nebraska | $134 | $69 | $1,608 |
| Nevada | $260 | $164 | $3,120 |
| New Hampshire | $85 | $52 | $1,020 |
| New Jersey | $257 | $181 | $3,084 |
| New Mexico | $133 | $65 | $1,596 |
| New York | $218 | $145 | $2,616 |
| North Carolina | $113 | $69 | $1,356 |
| North Dakota | $114 | $66 | $1,368 |
| Ohio | $117 | $65 | $1,404 |
| Oklahoma | $169 | $83 | $2,028 |
| Oregon | $156 | $91 | $1,872 |
| Pennsylvania | $162 | $90 | $1,944 |
| Rhode Island | $298 | $177 | $3,576 |
| South Carolina | $255 | $160 | $3,060 |
| South Dakota | $152 | $62 | $1,824 |
| Tennessee | $132 | $60 | $1,584 |
| Texas | $204 | $110 | $2,448 |
| Utah | $146 | $92 | $1,752 |
| Vermont | $140 | $57 | $1,680 |
| Virginia | $207 | $118 | $2,484 |
| Washington | $184 | $95 | $2,208 |
| West Virginia | $156 | $83 | $1,872 |
| Wisconsin | $125 | $57 | $1,500 |
| Wyoming | $94 | $50 | $1,128 |
These are the starting numbers the calculator uses before it adjusts for your answers.
Rates by state: see the full car insurance calculator by state for all 50 states, or open a state calculator for California, Texas, Florida and New York.
Car insurance cost by driver age
Age changes your price more than almost anything else. Here is what the national average full-coverage price looks like for each age group with a clean record.
| Driver age | Full coverage (monthly) | Compared with age 35–54 |
|---|---|---|
| 16–19 | $455 | about 2.6x |
| 20–24 | $280 | about 60% more |
| 25–34 | $184 | about 5% more |
| 35–54 | $175 | baseline |
| 55–64 | $166 | about 5% less |
| 65+ | $189 | about 8% more |
How tickets and accidents change your price
| Driving record | Full coverage (monthly) | Typical increase |
|---|---|---|
| Clean record | $175 | — |
| 1 speeding ticket | $214 | about 22% |
| 1 at-fault accident | $254 | about 45% |
| DUI / DWI | $324 | about 85% |
Most insurers look back 3 to 5 years. A DUI can stay on your rate for up to 10 years in some states, and you may also need an SR-22 form.
Can you get a car insurance quote without personal info?
You can get an estimate without personal info, but not a real quote. An estimate, like the one above, uses averages for drivers like you. A real quote is a price an insurer will actually sell you, and every U.S. insurer needs to check who you are before they can give one.
That is why most “anonymous quote” sites still ask for a ZIP code, a birthday or a phone number. Our calculator asks for none of these. Use it to get a fair idea of your price first, then share your details only with the two or three insurers you actually want to buy from.
Anonymous estimate vs. real quote
| Anonymous estimate (this calculator) | Real quote from an insurer | |
|---|---|---|
| What you share | State, car type, age range, record | Name, address, date of birth, license number, VIN, driving history |
| Time | Under 1 minute | 10–20 minutes per company |
| Calls and emails after | None | Often several |
| Accuracy | A fair price range | Your exact price |
| Can you buy a policy? | No | Yes |
| Credit check | No | Soft check in most states (does not hurt your score) |
How to get an anonymous car insurance quote, step by step
- Get a no-info price range. Use a calculator that needs only your state, car type, age range and driving record. Note the monthly range for the coverage level you want.
- Shortlist two or three insurers. Pick companies known to be cheap for your profile (young drivers, drivers with a ticket, high-mileage drivers and so on).
- Make a spare email address. Use it only for insurance forms so sales emails never reach your main inbox.
- Skip optional fields. Leave the phone number blank when it is optional and untick any “contact me” or “share with partners” boxes.
- Get quotes straight from insurer websites. A direct quote goes to one company. A lead-generation site can pass your details to many agents.
- Compare like for like. Use the same liability limits, deductible and add-ons on every quote, or the cheapest price may just be less coverage.
- Share full details only when you buy. Your license number, VIN and Social Security number are only truly needed at the final step.
What each quote method asks you to share
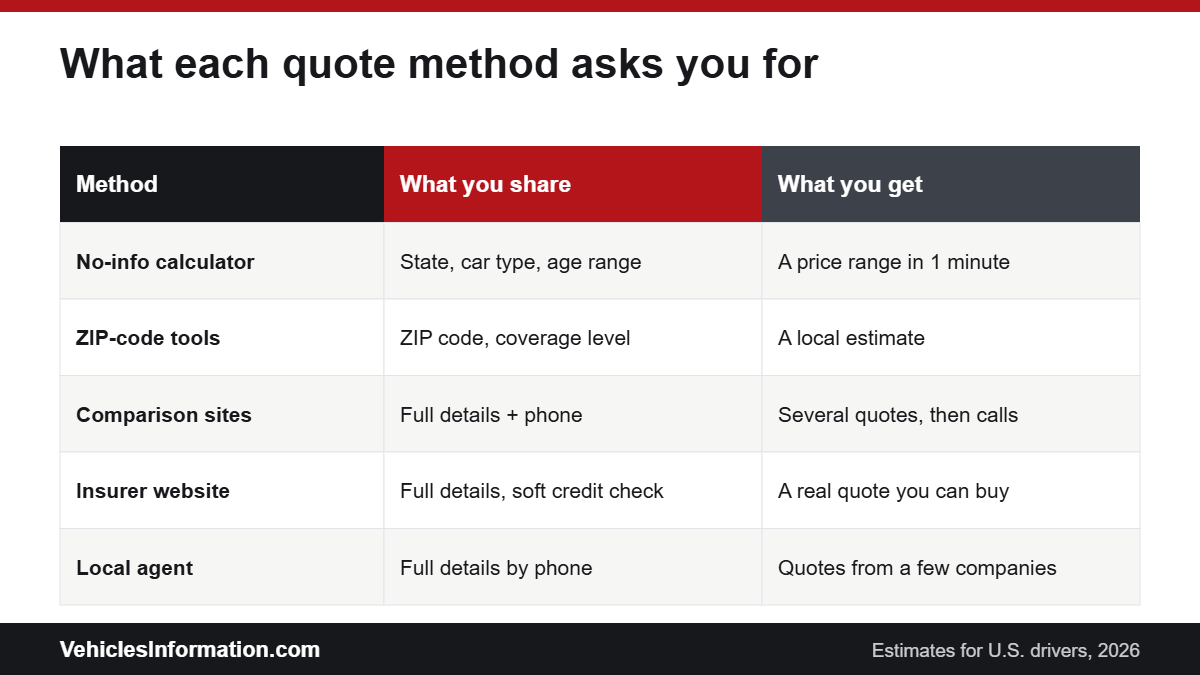
| Method | Personal info needed | Calls or emails after? | Accuracy |
|---|---|---|---|
| No-info calculator | None | No | Price range |
| ZIP-code estimate tool | ZIP code | Usually no | Local price range |
| Comparison site | Name, birth date, address, phone, email | Often yes | Close to real |
| Insurer website | Name, birth date, address, license, VIN | Sometimes | Exact |
| Local agent | Same as insurer, by phone or in person | Yes | Exact |
Why insurers ask for personal information
- Name and date of birth: to pull your driving record (MVR) and claims history (CLUE report).
- Address or ZIP code: theft, crash and repair costs differ from one street to the next.
- Driver’s license number: to check tickets, accidents and license status.
- VIN: to confirm the exact trim, safety features and past damage of your car.
- Social Security number (sometimes): to run a soft credit check for a credit-based insurance score. This does not lower your credit score.
How to protect your privacy when you shop for quotes
- Start with this calculator so you only contact insurers when you are close to buying.
- Get quotes straight from insurer websites instead of “lead” sites that sell your details to many agents.
- Use a separate email address for quote forms.
- Skip the phone number field when it is optional, and say no to “contact me” boxes.
- Read the privacy policy and look for a “Do not sell my information” link.
State minimum, standard or full coverage: which do you need?
| Coverage level | What it pays for | Who it suits |
|---|---|---|
| State minimum | Damage and injuries you cause to others, up to your state’s legal minimum | Older, low-value cars and tight budgets |
| Standard | Higher liability limits (often 100/300/100) plus uninsured motorist cover | Most drivers who own their car outright |
| Full coverage | Liability plus collision and comprehensive, which fix or replace your own car | Newer cars, and any car with a loan or lease |
If you have a car loan or lease, the lender will require full coverage. If your car is worth less than about $4,000, or less than ten times your yearly collision cost, dropping collision often makes sense.
10 ways to lower your car insurance cost
- Compare at least three insurers every year. Prices for the same driver can differ by hundreds of dollars.
- Raise your deductible to $1,000 if you have the savings to cover it.
- Bundle car insurance with home or renters insurance.
- Ask about a safe-driver or telematics program that tracks how you drive.
- Pay for six or twelve months at once instead of monthly.
- Keep your record clean and take a defensive driving course where it earns a discount.
- Improve your credit if you live in a state that uses it.
- Drop collision and comprehensive on an old, low-value car.
- Ask for good-student, military, and low-mileage discounts.
- Check insurance costs before you buy a car. A minivan or small SUV is usually far cheaper to insure than a sports car.
Shopping for a new car? Our guides to the 2027 Toyota RAV4, 2027 Honda HR-V and 2027 Toyota Sienna cover prices and trims, and Honda owners can use our Honda insurance calculator for a model-by-model estimate.
Frequently asked questions
Is this car insurance calculator really free and anonymous?
Yes. It runs in your browser. We do not ask for or store your name, email, phone number, ZIP code or license number.
How accurate is a car insurance estimate without personal info?
It gives you a fair price range for drivers like you. Your real price can still be higher or lower because of your exact ZIP code, claims history and the insurer you choose.
How much is car insurance per month?
The U.S. average is about $175 a month for full coverage and about $98 a month for liability-only cover in 2026. Your own price depends mostly on your state, age and driving record.
Does getting a car insurance quote hurt my credit score?
No. Insurers use a soft credit check, which does not affect your score.
Can I get a car insurance quote without a phone number?
Many insurer websites let you skip the phone field or mark it optional. Lead-generation sites usually require it because they pass it to agents.
Can I buy car insurance anonymously?
No. To buy a policy, an insurer must confirm your identity, driving record and the vehicle you are insuring.
What is the cheapest state for car insurance?
New Hampshire is the cheapest, at about $85 a month for full coverage, followed by Wyoming and Idaho.
Why is my car insurance so expensive?
The most common reasons are living in a high-cost state or city, being under 25, a recent accident or ticket, low credit, or driving a car that costs a lot to repair.
VehiclesInformation Editorial Team
The VehiclesInformation Editorial Team researches and writes our car and car insurance guides for U.S. drivers. Insurance figures are checked against state insurance department rules and published 2026 rate studies, and pages are updated when laws or rates change. Read how we estimate car insurance costs.